 Analysis by Appwee
My first impression of Affirm is that it makes a drawn-out purchase feel unusually simple: browse, consider a payment plan, and see the commitment laid out before deciding. That ease is appealing during the first week, especially when you are comparing a few items and want to know whether spreading a cost would fit your budget. I’d treat that convenience as a way to evaluate a purchase, not as a reason to buy something I would otherwise leave on the shelf.
A useful first-week test
Rather than starting with an impulse buy, I’d use the app for something already on my shopping list. Check whether the retailer offers Affirm at checkout, review the plan shown for that specific purchase, and compare the total with paying upfront. The key question is not simply whether a monthly amount looks manageable; it is whether the whole commitment still makes sense beside rent, bills, savings, and any other payments you already have.
This small routine helps separate a genuine budgeting choice from the psychological pull of a lower-looking installment. I’d also decide in advance what kinds of purchases qualify for this approach. A necessary replacement for a broken appliance may be easier to justify than an upgrade you only started considering after seeing a promotion. That personal rule can keep the app useful without letting it quietly expand your shopping list.
Where it fits among shopping options
Affirm is a shopping app from Affirm, Inc, designed around paying over time rather than simply collecting products in a conventional store catalog. Compared with putting an item on a credit card, the practical advantage is being able to review a purchase-specific payment option before committing. Compared with saving first, the trade-off is equally clear: you get the item sooner, but you take on a future obligation instead of waiting until the money is already set aside.
Neither approach is automatically best. If I can comfortably pay upfront without disturbing money reserved for essentials, that is usually the simpler choice. If the purchase is urgent and a payment plan has terms I can manage, Affirm may be worth checking. If the plan would make my monthly budget tight, saving longer or choosing a less expensive alternative is likely wiser. I would not treat the app as a substitute for a cash-flow plan or as proof that an item is affordable.
Making the payment view work for you
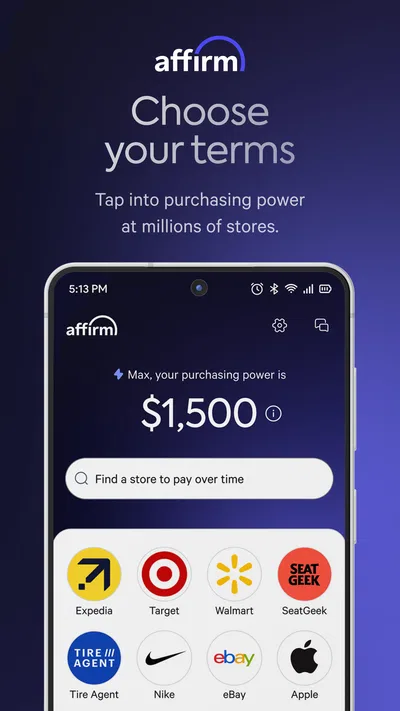
A practical habit is to look at each plan in the context of all the others, not as a series of isolated decisions. Before agreeing to another purchase, I’d total the payments I already expect to make and ask whether the combined amount leaves room for ordinary surprises. A dashboard can make individual commitments easier to see, but the useful part is the review: checking what is due, spotting a crowded month, and pausing before adding one more installment.
For a realistic example, imagine a laptop stops working just before a busy stretch at work or school. I’d compare replacement options, check whether a payment plan is available for the model that actually meets my needs, and weigh its full cost against a more affordable device or a short delay. If the plan fits without relying on optimistic assumptions about next month, spreading the payment might help. If it only works when nothing unexpected happens, I’d take that as a reason to reconsider.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
What to check before committing
Do not assume that every purchase will present the same payment choices. The options shown at checkout are the ones to assess for that transaction, and I’d read the terms there rather than relying on what appeared for an earlier item. Check the payment amounts, timing, and total you will owe, then make sure the dates work with your usual income and bill schedule. A plan that looks comfortable in isolation can feel different when several obligations land close together.
I’d also decide how I want to keep track of due dates before making the first purchase. Alerts and reminders can help, but they work best as a backup to a routine: review upcoming payments regularly and keep enough room in the budget for them. If you share household expenses or use more than one payment method, include those commitments in the same mental checklist. That extra step is more reliable than assuming one app view represents your whole financial picture.
Who will get the most from it
Affirm makes the most sense for shoppers who already know what they intend to buy, value seeing a payment schedule before checkout, and are comfortable monitoring future obligations. It can be handy for a planned replacement or a purchase whose timing matters, provided the specific terms work for your finances. The app is free, rated for Everyone, and has an average rating of 4.8 from around 561,000 ratings, with over 10 million installs. Those figures show broad adoption, but they cannot tell you whether a particular plan suits your budget.
I’d be more cautious if you tend to shop when stressed, lose track of recurring commitments, or find installments make optional purchases feel harmless. In that case, paying upfront, waiting until you have saved the full amount, or buying a lower-cost alternative may offer better control. Someone who wants a traditional shopping app focused mainly on browsing products may also find Affirm’s payment-centered role narrower than expected.
How it holds up beyond the novelty
The lasting value here depends less on opening the app often and more on using it deliberately when a suitable purchase comes up. It is not a reason to create a monthly shopping habit. If you use it rarely, to compare a real payment option and keep the obligation visible, that can still be useful. If you find yourself checking for things to buy because paying later feels easier, the same convenience becomes a source of fatigue.
There is some ongoing maintenance involved: keep your account details current, pay attention to reminders, and review active commitments rather than letting them fade into the background. I would not call that a heavy burden, but it does require attention. The app can organize information about its purchases; it cannot decide whether your overall spending is sustainable or make room in a crowded budget.
Getting Started with Affirm
The first thing you notice when you open the Affirm app is its clean, user-friendly interface. Signing up is a breeze. You just need to enter a few details like your name, email, and phone number, and you’re good to go. What I love about Affirm is that it doesn't dive into your credit score pool, so you’re not going to see any surprise dips when you check your credit report.
How It Works
Once you’re set up, using Affirm is pretty straightforward. You shop as you normally would at your favorite stores, and when you check out, you choose Affirm as your payment method. The app offers flexible payment options, usually letting you choose between three, six, or twelve-month plans. What’s really cool is that it shows you exactly how much you’ll pay each month, so there are no sneaky surprises later on. Honest transparency is rare these days, and Affirm nails it.
Shopping with Flexibility
Browsing through the app, I found a wide range of retailers partnered with Affirm. Whether you’re looking for electronics, fashion, or even travel experiences, the app has options galore. You can even use Affirm for more substantial purchases like a new laptop or that dream vacation.
"Affirm lets you stretch your budget without stretching your patience."
Now, I’m someone who likes to keep things organized, and the app’s dashboard lets you track all your purchases and payments in one place. It’s honestly like having a mini financial assistant in your pocket, helping you keep tabs on your spending without breaking a sweat.
Security and Peace of Mind
One thing that caught my attention was the app’s focus on security. They use encryption to keep your data safe. Plus, they don’t sell your data to third parties, which is a huge plus in my book. Knowing my information is secure gives me that extra peace of mind when making purchases.
Affirm in Everyday Life
Let me paint you a picture: you’re at a store, and you see a killer deal on a new TV. Instead of walking away with regret, you whip out your phone, open the Affirm app, and in a few taps, you’ve got a payment plan that fits your budget. No need to wait until payday or dip into your savings. It’s all about making it work for you.
Another nifty feature is the ability to set up alerts and reminders so you’ll never miss a payment. Trust me, I’ve been there, and it’s a lifesaver to have these little nudges keeping you on track.
Final Thoughts
In the fast-paced world of technology, having options like Affirm can make a world of difference. It’s not just about buying things; it’s about buying smartly. Whether you’re a savvy shopper or someone looking to manage finances better, this app has something to offer. With its transparency, ease-of-use, and security features, Affirm stands out as a solid choice for those looking to make their money go further.
So, next time you spot that perfect item, remember that Affirm might just be your ticket to making it your own, sooner rather than later. Happy shopping!
A final budget check
One point I would keep in mind is that an installment plan changes when money leaves your account, not the underlying cost of the item. Before confirming, I’d compare the displayed total with the price I would pay another way and consider whether I am choosing the plan for convenience or because I cannot afford the purchase. That distinction matters. If affordability depends on stretching the payment, I would slow down and check whether a cheaper model, repair, or postponement solves the problem with less pressure.
For people wondering whether this is a good app to keep installed, my answer is: only if its role stays clear. Affirm is a free shopping app, currently at version 3.402.1, and it has been available since June 20, 2016. It runs on Android 7.0 or later. I see its recurring value in making a specific checkout decision easier to inspect, rather than in daily browsing or constant use. When I have no planned purchase, I do not need to open it just to find another reason to spend.
Overall, I’d recommend considering Affirm if you want to compare a purchase-specific plan with paying upfront and are willing to keep an eye on your commitments. I would skip it if installments encourage you to buy more than you planned, or if another due date would add stress to an already tight month. The app’s convenience is real, but the best long-term habit is still deliberate shopping: decide what you need, read the terms for that purchase, and leave the checkout if the numbers do not feel comfortable.
Affirm: Buy now, pay over time Pros and Cons
- Flexible payment options for budgeting
- User-friendly interface for easy navigation
- No hidden fees, transparency ensured
- Quick approval process for purchases
- Wide range of partner retailers available
- High interest rates may apply
- Limited to select stores and items
- Requires a soft credit check
- Payments can't be adjusted once set
- May encourage unnecessary spending
Affirm: Buy now, pay over time Frequently Asked Questions
What is Affirm and how does it work?
Affirm is a flexible payment option that allows you to buy items now and pay for them over time. It partners with various retailers to offer installment plans, allowing you to pay off purchases in fixed monthly payments. The app provides transparency by showing the total interest upfront, ensuring no hidden fees.
Are there any interest rates or fees associated with Affirm?
Affirm offers loans with interest rates ranging from 0% to 30% APR, depending on your creditworthiness and the retailer. There are no hidden fees, late fees, or penalties for early payments. The app clearly displays the total cost and interest before you finalize your purchase, so you’re fully informed.
How does Affirm affect my credit score?
When you apply for an Affirm loan, it performs a soft credit check that does not affect your credit score. However, making timely payments can positively impact your credit report. Late payments might be reported to credit bureaus, so it’s important to pay on time to maintain a good credit standing.
What are the eligibility requirements for using Affirm?
To use Affirm, you must be at least 18 years old, a resident of the U.S., and have a valid U.S. or APO/FPO/DPO address. You’ll need to provide your Social Security number and a U.S.-based mobile number. Eligibility also depends on your credit score and financial history.
Is it safe to use Affirm for online shopping?
Yes, Affirm is designed with security in mind. It uses encryption and industry-standard security measures to protect your personal information. The app also offers transparency by showing clear payment terms and ensuring there are no hidden fees, making it a reliable option for online shopping.
Gallery